
Categories
Mortgage MinutePublished September 21, 2026
Buying a Home? Look Beyond the Purchase Price
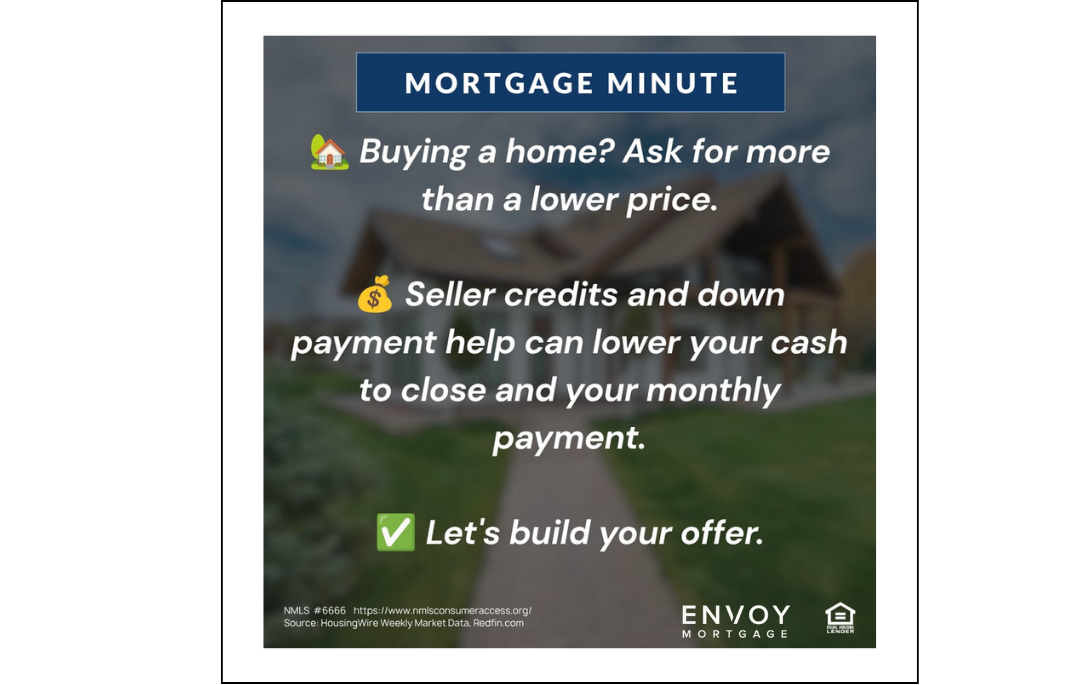
Buying a Home? Your Offer Is About More Than the Purchase Price
When buyers think about negotiating on a home, the purchase price usually gets most of the attention. Getting a seller to accept less can certainly make a difference, but price is only one part of the financial picture.
For today's buyers, a well-structured offer may also address the amount of cash needed at closing and the monthly payment after the keys are handed over. Depending on the property, financing, seller's circumstances, and loan requirements, seller credits, a mortgage rate buydown, or an eligible down payment assistance program could potentially help with one of those goals.
That matters when mortgage rates remain a major affordability concern. Instead of focusing exclusively on the asking price or waiting for the market to change, buyers can look at the entire transaction and determine which terms would make the biggest difference for their situation.
For buyers throughout Napa, Sonoma, Solano, Marin, Contra Costa, Alameda, and San Francisco, that starts with knowing your numbers before you write the offer.
Start With the Payment You Can Comfortably Afford
A home search often begins with a price range, but the purchase price doesn't tell you exactly what it will cost to own the home each month.
Your mortgage payment is affected by the loan amount, interest rate, loan program, down payment, property taxes, homeowners insurance, and potentially HOA dues and mortgage insurance. Two homes with similar asking prices can produce different monthly costs.
That's why it can be helpful to begin the conversation with your lender before getting too far into the home search.
Knowing the monthly housing payment that fits comfortably within your budget gives you and your real estate agent a much better framework for evaluating properties. It also gives your lender an opportunity to explain the financing options available to you.
Once those numbers are clear, the conversation can move beyond simply negotiating the price.
Seller Credits Can Change the Numbers
Depending on the transaction and loan program, a seller credit may be used toward certain allowable buyer expenses, including eligible closing costs or some financing costs.
That can be valuable for a buyer who wants to preserve more cash after purchasing the home.
Closing costs are separate from the down payment and can include expenses associated with the loan and completing the transaction. A buyer who has enough money for the down payment may still prefer to keep additional funds available for moving expenses, repairs, furnishings, emergency savings, or simply maintaining a comfortable financial cushion after closing.
In the right situation, negotiating a seller contribution toward eligible closing costs could help.
For another buyer, the monthly payment may be a bigger concern than the amount of cash required upfront. Depending on the loan and lender requirements, an allowable seller credit might instead be used toward a mortgage rate buydown.
The best option isn't necessarily the one with the biggest credit. It's the one that addresses the buyer's actual financial priority.
A Lower Price Isn't Always the Only Goal
Imagine a buyer negotiating on a home where the seller has some flexibility.
One approach could be to concentrate entirely on lowering the purchase price. Another could involve negotiating an allowable seller credit that helps with closing costs or financing.
Those two options affect the buyer differently.
A lower purchase price reduces the amount paid for the property and may slightly reduce the amount financed. A seller credit, when permitted, may reduce certain upfront expenses or potentially help with financing costs.
Which creates more value depends on the numbers.
That's why it makes sense to have the lender involved before the offer is written. The lender can model different scenarios so the buyer understands how a price adjustment, seller credit, or financing option would affect both the cash required to close and the monthly payment.
The agent can then use that information when developing an offer strategy for the particular property.
Down Payment Assistance May Be Another Option
Seller credits aren't the only tool buyers may want to explore.
Some buyers may qualify for down payment or closing-cost assistance programs. Others may have access to loan options that require a smaller down payment than they initially expected.
Eligibility depends on the specific program and can include requirements related to income, purchase price, location, occupancy, loan type, or other factors. Program availability and guidelines can also change.
For that reason, buyers shouldn't assume they qualify for assistance—or assume they don't.
A conversation with a qualified lender can help identify programs that are currently available and determine whether any fit the buyer's circumstances.
This can be especially important for buyers who are financially comfortable with the ongoing monthly payment but are concerned about using too much of their savings to complete the purchase.
The Opportunity Depends on the Home
Northern California isn't one uniform housing market.
Conditions in Napa can look different from Sonoma. Solano and Contra Costa can behave differently from Marin or San Francisco. Alameda County adds another set of neighborhood and price-point differences.
Even within the same city, two homes can have completely different negotiating environments.
A well-priced property that has just come on the market and is generating significant buyer interest may provide very little room for negotiation. Another home that has been available longer, has undergone a price adjustment, needs repairs, or is competing against several similar listings may present more possibilities.
That's why asking for a seller credit shouldn't be an automatic part of every offer.
EO&A can look at the individual property, recent comparable sales, competing listings, pricing history, time on market, and current activity to help determine what kind of offer makes sense.
The goal isn't to ask for more simply because you can. It's to structure an offer around the buyer's priorities while remaining competitive for the home.
Higher Rates Make Offer Strategy More Important
When mortgage rates are elevated, buyers naturally pay closer attention to the monthly payment.
That's exactly why the structure of the offer deserves attention too.
If a buyer is concerned about the payment, the lender can help determine whether an available financing strategy could make a meaningful difference. If the bigger concern is cash needed at closing, the conversation may instead center on allowable seller credits, down payment options, or assistance programs.
Sometimes the numbers will show that negotiating the purchase price is the strongest option. Other times, a different structure may better address what the buyer is trying to accomplish.
There isn't one answer that works for every purchase.
There is simply a better opportunity to make those decisions when you understand the numbers before negotiations begin.
Preparation Gives Buyers More Options
One of the most useful things a buyer can do right now is prepare before finding the home they want.
That means having a lender review the financing, understanding the estimated cash needed at closing, knowing the monthly payment range that feels comfortable, and discussing potential offer strategies with an agent.
Doing that work early changes the experience when the right home comes along.
Instead of finding a property and then scrambling to determine whether the numbers work, the buyer already has a framework. The agent can evaluate the home and the seller's position while the lender can quickly model the financing.
That creates a much more informed offer.
Build the Offer Around Your Numbers
The asking price is important, but it doesn't tell the whole story.
The monthly payment matters. The cash needed to close matters. The amount you want to keep in savings matters. The financing matters. And depending on the property, the terms you're able to negotiate with the seller can matter too.
If you're already looking for a home in Napa, Sonoma, Solano, Marin, Contra Costa, Alameda, or San Francisco, this is a good time to make sure you understand all of those pieces.
EO&A can help you evaluate the home, comparable sales, competing inventory, and the seller's position before deciding how to structure your offer. Your lender can help determine how different financing options, seller credits, or eligible assistance programs affect your actual numbers.
Then, when the right home appears, you're not simply deciding what price to offer.
You're building an offer around what works for you.
Happy house hunting 🏡
Sources: HousingWire Weekly Market Data; mortgage and financing information supplied by Envoy Mortgage; specific loan, seller-contribution, and assistance-program requirements should be confirmed with the buyer's lender.
Common Questions About Seller Credits and Buyer Assistance
What can seller credits be used for when buying a home?
Seller credits may be used for certain buyer expenses permitted by the loan program and purchase agreement, including eligible closing costs and, in some situations, financing costs such as a mortgage rate buydown. The amount a seller can contribute and how the funds may be used depend on the buyer's financing. Buyers should have their lender confirm the applicable requirements and limits before requesting a credit in an offer.
Can I ask a seller to help with closing costs?
Yes, buyers can request a seller contribution toward eligible closing costs. Whether the seller agrees will depend on the individual transaction, and loan programs may limit the amount a seller is permitted to contribute. The property's pricing, competition, time on market, and seller's circumstances can also affect whether requesting a credit makes sense. Your agent and lender can help determine an appropriate strategy before the offer is written.
Is a seller credit better than asking for a lower purchase price?
Neither is automatically better. A lower purchase price reduces the amount paid for the property, while an allowable seller credit may help reduce certain upfront expenses or financing costs. The better option depends on the buyer's loan, available cash, monthly payment goals, and the amount being negotiated. Comparing both scenarios with the lender before making an offer can help buyers understand which provides more value for their situation.
Can seller credits be used for a mortgage rate buydown?
Seller credits may be used toward certain mortgage rate buydowns when permitted by the buyer's loan program and lender. The financial effect depends on the type of buydown, loan terms, amount of the credit, and other requirements. Buyers considering this strategy should ask their lender to calculate the actual payment and explain how the buydown works before deciding whether it is the best use of a negotiated seller contribution.
Are down payment assistance programs available to California homebuyers?
California homebuyers may have access to down payment or closing-cost assistance programs depending on factors such as income, location, loan program, property, and occupancy requirements. Programs and eligibility guidelines can change, so buyers should confirm current options with a qualified lender. Even buyers who assume they won't qualify may benefit from asking what programs are available before determining how much cash they will need to purchase a home.
Search Homes • Explore Financing Resources • Meet the EO&A Team
Contact EO&A today to schedule your free home value review.
Your Trusted Real Estate Advisors across Northern California
Whether you’re planning to sell in San Francisco, Marin, Napa, Sonoma, Solano, Yolo, Sacramento, Contra Costa, or Alameda County, our team has local experts ready to help you navigate your next move with confidence and strategy.
EO&A Team
Elizabeth, Anne, Ian, Ksenia, Cliff, Annie, Mike, Nina, Sidra, Karen, Annie, Steven, Gladys, Venus, Najat, and Courtney
707.312.0819 • hello@eoanda.com • www.eoanda.com
DRE# 01388551 • GUIDE Real Estate DRE# 01976964
Real estate and financing information is provided for educational purposes only. Mortgage programs, rates, qualification requirements, seller concessions, and market conditions can change. Buyers should consult their lender and appropriate professional advisors regarding their individual financial situation.
Anne Kennedy
Broker Associate | EO&A | Real Estate in Napa, Sonoma, Solano, Marin, and San Francisco
or another way