
Categories
Mortgage Minute, Market UpdatesPublished November 2, 2026
Still Renting? Your Down Payment May Not Be as Big a Hurdle as You Think
Still Renting? Your Down Payment May Not Be as Big a Hurdle as You Think
You've been paying rent every month, keeping up with your bills, and putting a little money aside whenever you can. Buying a home is something you'd like to do, but every time you think about the down payment, it feels like the finish line moves a little farther away.
Maybe you've even looked at homes online and wondered whether owning one could be possible sooner than you expected.
If the down payment is the main reason you haven't started looking seriously, there's something worth knowing: you may have more options than you realize.
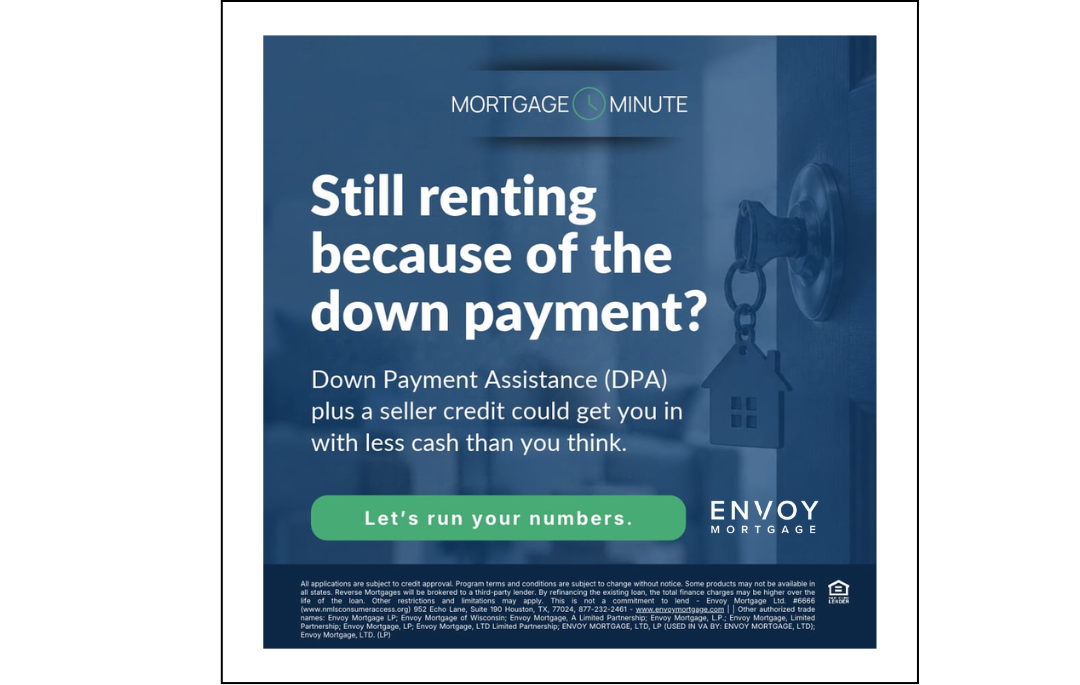
This week's Mortgage Minute from Envoy Mortgage highlights two ways eligible buyers may be able to reduce the amount of cash they need to purchase a home: down payment assistance programs and seller credits toward closing costs.
And with mortgage rates improving for four consecutive weeks, according to the update provided by Envoy, it may be a good time to find out what those options could mean for your own budget.
You don't need to have every dollar saved before starting that conversation.
The Down Payment Isn't Always What Buyers Expect
One of the biggest misconceptions about buying a home is that you need to save an enormous amount of money before you can even begin.
It's easy to see why. When you're looking at home prices in Napa, Sonoma, or other Northern California communities, even a relatively small percentage of the purchase price can feel intimidating.
And saving isn't always straightforward. Rent, groceries, transportation, childcare, and everyday expenses all compete for the same dollars.
For someone who's been working toward homeownership for years, the thought of needing to save even more can be discouraging.
But the amount you need for a down payment depends on the financing available to you. Not every buyer has to approach the purchase the same way.
This week's Envoy Mortgage update points to down payment assistance programs that may help eligible buyers cover the down payment on certain FHA and USDA loans. Some assistance options may even offer forgiveness after five years, depending on the program's requirements.
That doesn't mean every buyer will qualify, or that every program provides the same benefit. The lender needs to review your circumstances, the loan program, and the specific assistance options available.
Still, it's worth having that conversation before assuming homeownership is years away.
Down Payment Assistance Could Change Your Timeline
Imagine you've been saving consistently, but you're still short of the amount you believe you'll need to purchase a home.
You may have already decided to renew your lease for another year while you continue putting money aside.
Now imagine sitting down with a lender and learning that you may qualify for a program that helps with some or all of the required down payment.
That could change the conversation considerably.
Down payment assistance, often called DPA, is designed to help eligible buyers address one of the upfront financial requirements of purchasing a home.
As Envoy explains in this week's update, certain programs can provide assistance in connection with FHA or USDA financing. Some options may also include forgiveness provisions after five years.
The important word is may.
Assistance programs have their own qualification requirements, conditions, and restrictions. Some forms of assistance may need to be repaid, while others may offer forgiveness when specific requirements are met.
Your lender can explain how the available programs work, whether you're eligible, and what obligations come with accepting assistance.
It's also important to look at the entire financial picture. Reducing the cash needed upfront doesn't automatically mean the ongoing mortgage payment will be affordable.
A good financing conversation should cover both.
Don't Forget About Closing Costs
The down payment gets most of the attention, but it isn't the only expense buyers need to prepare for.
There are also closing costs associated with completing a home purchase. These can include lender-related expenses, title and escrow services, and other eligible transaction costs.
For someone who has been saving toward a down payment, discovering those additional expenses can be frustrating.
This is where seller credits may become part of the discussion.
Depending on the property, purchase agreement, and financing requirements, a buyer may be able to negotiate a contribution from the seller toward eligible closing costs.
That can help reduce the amount of money the buyer needs to bring to closing.
Consider a buyer who qualifies for down payment assistance but still needs additional funds for closing expenses. If the seller is willing to provide an allowable credit, those two strategies may work together to address different parts of the upfront cost.
They aren't interchangeable, and the lender must confirm whether the assistance program and seller contribution can be combined under the applicable rules.
But understanding both options can help buyers approach the purchase with a more complete plan.
Instead of focusing exclusively on saving a larger down payment, you can begin looking at what the transaction would actually require.
Why This Fall May Be Worth Another Look
The timing of this week's Mortgage Minute is interesting for buyers who have been waiting.
According to the information Envoy provided, mortgage rates have improved for four consecutive weeks. There's no guarantee that trend will continue, but it means buyers who received financing estimates a month ago may want to request updated numbers.
At the same time, more homes are available nationally than at this point last year, and more than four in ten homes for sale have experienced a price reduction.
Those are national figures from the supplied market update, not statistics for individual Northern California counties.
They do, however, provide context for the conversations buyers may be able to have with sellers.
A home that's been on the market for several weeks may present a different negotiating situation than one that was listed yesterday. A seller who has already reduced the asking price may be willing to discuss other terms, including an allowable credit toward closing costs.
That doesn't mean every seller will agree, and buyers shouldn't assume that a price reduction guarantees additional concessions.
The opportunity depends on the property and the seller's circumstances.
There's also the seasonal side of the market. As the holidays approach, fewer buyers are typically out shopping. For someone who's financially prepared, that quieter pace may make it easier to consider available homes without the same level of competition.
If you've been waiting to begin your search, it's worth understanding what homes are available and what financing might look like today.
What Buying Could Look Like in Northern California
One of the reasons we encourage buyers to talk with a lender early is that home prices and financing needs vary so much across Northern California.
Someone looking for a first home in Napa may have a different budget and set of priorities than a buyer considering Fairfield, Vacaville, Santa Rosa, or Benicia.
Even within the same city, your options can change depending on the neighborhood, type of home, and price range.
At EO&A, we can help you explore the communities and properties that fit your goals while your lender reviews the financing side.
You may find that your budget allows you to consider more homes than you expected. Or you may decide to adjust your search to a different area or property type.
There's no need to make those decisions based on an assumed down payment requirement.
Start with what you can comfortably afford each month, how much savings you'd like to keep after closing, and what financing options may be available.
From there, we can help you look at homes that make sense for your situation.
And if you're considering a property where the seller may be open to negotiating, we can discuss whether requesting a closing-cost credit would be appropriate.
The goal isn't simply to find a way to purchase a home sooner. It's to find a home and financing arrangement that you can feel comfortable maintaining.
Start With a Conversation, Not Another Year of Waiting
It's easy to put off talking with a lender because you don't think you're ready.
Maybe you want to save another $10,000. Maybe you're hoping mortgage rates will come down further. Or perhaps you're waiting until you have a clearer picture of what you want.
Those are reasonable considerations, but you don't need to have everything figured out before asking questions.
A lender can help you understand the amount you may qualify to borrow, the estimated monthly payment, and how much cash you would need to complete a purchase.
They can also review whether down payment assistance is available for your situation and explain how those programs work.
If you're not ready yet, you'll have a better idea of what to work toward.
Perhaps you need more savings, a different price range, or additional time before making a purchase. Having that information gives you a specific goal instead of an assumption about how much money you need.
And if the numbers show that you're closer than you thought, you can begin exploring homes with a clearer understanding of your options.
Homeownership May Be Closer Than You Think
Renting while saving for a home can feel like a long process, especially when housing costs are already taking up a significant part of your monthly budget.
But the down payment doesn't always have to be the obstacle that keeps you from exploring homeownership.
Down payment assistance programs may help eligible buyers with the upfront investment. Seller credits may help cover certain closing expenses. And recent improvements in mortgage rates make this a reasonable time to ask your lender for updated estimates.
None of those options guarantees that buying is the right decision today.
What they can do is help you understand whether your plans are realistic and what steps would move you closer to your goal.
If you're renting in Napa, Sonoma, Solano, Marin, Contra Costa, Alameda, or San Francisco and wondering what it would take to purchase your first home, EO&A can help you explore your options.
We'll work with you to identify homes and communities that fit your needs, while a qualified lender can review available assistance programs and financing.
You may discover that you still have some saving to do. Or you may find that the down payment isn't as far out of reach as you assumed.
Either way, you'll have a clearer picture of what's possible.
Happy house hunting 🏡
Source: Weekly Mortgage Minute information and graphic supplied by Envoy Mortgage, with mortgage-rate commentary attributed to Mortgage News Daily. Market statistics are national figures supplied in the update and may not reflect individual Northern California markets. Down payment assistance programs, forgiveness provisions, seller contributions, and loan eligibility are subject to specific program requirements and availability. Buyers should confirm current options and obligations with a qualified lender.
Frequently Asked Questions About Down Payment Assistance
What is down payment assistance for homebuyers?
Down payment assistance, commonly called DPA, refers to programs that help eligible homebuyers cover some or all of the down payment required to purchase a home. The assistance may be structured differently depending on the program, and some options have repayment or forgiveness requirements. This week's Envoy Mortgage update highlights assistance associated with certain FHA and USDA loans. Buyers should ask a qualified lender which programs are available and whether they meet the eligibility requirements.
Can I buy a home in California without saving the entire down payment myself?
Some eligible buyers may be able to use down payment assistance to cover part or all of the required down payment, depending on the loan and assistance program. However, buyers may still need funds for other purchase expenses, and program rules can vary. A lender can review your finances, determine which options may be available, and estimate how much cash you would actually need to complete a home purchase.
Do down payment assistance programs have to be repaid?
Repayment requirements depend on the specific down payment assistance program. Some assistance options may need to be repaid, while others may offer forgiveness after certain conditions are met. The Envoy Mortgage update mentions programs that may provide forgiveness after five years. Buyers should carefully review the terms with their lender, including any repayment obligations, occupancy requirements, or conditions that could affect forgiveness.
Can I combine down payment assistance with seller credits?
Down payment assistance and seller credits may be used together in some transactions, subject to the applicable loan and assistance-program rules. Down payment assistance may help with the down payment, while an allowable seller credit may help cover eligible closing costs. The lender must confirm whether the combination is permitted and explain any contribution limits. Buyers should review these options before making an offer so they understand the actual cash required.
Is the holiday season a good time for first-time homebuyers to look for a home?
The holiday season can offer opportunities for buyers because fewer people may be actively searching, as noted in this week's Mortgage Minute. That can mean less competition for certain properties, although the number of available homes may also change. Whether it's a good time to buy depends on your finances, the homes available, and local market conditions. First-time buyers should begin with their budget and financing options rather than trying to predict the perfect time to purchase.
Search Homes • Buyer Services • Meet the EO&A Team
Contact EO&A today to schedule your free home value review.
Your Trusted Real Estate Advisors across Northern California
Whether you’re planning to sell in San Francisco, Marin, Napa, Sonoma, Solano, Yolo, Sacramento, Contra Costa, or Alameda County, our team has local experts ready to help you navigate your next move with confidence and strategy.
EO&A Team
Elizabeth, Anne, Ian, Ksenia, Cliff, Annie, Mike, Nina, Sidra, Karen, Annie, Steven, Gladys, Venus, Najat, and Courtney
707.312.0819 • hello@eoanda.com • www.eoanda.com
DRE# 01388551 • GUIDE Real Estate DRE# 01976964
Information is provided for general educational purposes. Property availability, pricing, and open-house schedules can change. Confirm current details with a licensed real estate professional.
Anne Kennedy
Broker Associate | EO&A | Real Estate in Napa, Sonoma, Solano, Marin, and San Francisco
or another way