
Categories
Mortgage MinutePublished October 5, 2026
Fewer Buyers, More Negotiating Room: What Higher Mortgage Rates Mean Right Now
Fewer Buyers, Better Deals: What Higher Mortgage Rates Mean Right Now
Mortgage rates climbed above 7.5% last week. For anyone already watching affordability closely, that’s probably not the news they wanted.
It’s also not the whole story.
Higher rates tend to thin out the buyer pool. Some people pause their search. Others adjust their budget or decide to wait. Meanwhile, homes that don’t sell quickly keep accumulating days on market, and sellers have to decide whether to hold firm or make a change.
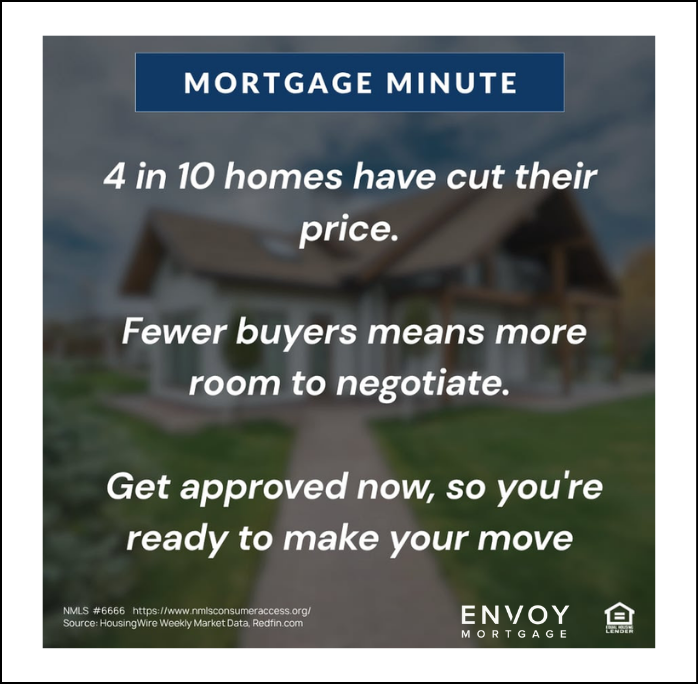
We’re seeing evidence of that nationally. HousingWire’s late-September market data showed price reductions on 42.5% of active listings. Mortgage News Daily’s daily index ended October 2 at 7.57% for a top-tier 30-year fixed mortgage scenario.
So yes, borrowing is more expensive. But for buyers who can comfortably afford to purchase at today’s rates, there may be another side to this market: less competition and more room to have a conversation with the seller.
Sometimes the Best Opportunity Has Been Sitting There for a While
It’s easy to get excited about the newest homes to hit the market. There’s something about a fresh listing that makes buyers feel like they need to see it immediately.
Right now, we’d pay just as much attention to the homes that have been sitting.
Maybe a house has been on the market for 35 days. Maybe the seller already reduced the price once. Maybe a similar home came up for sale nearby and suddenly buyers have another option.
None of those things automatically make it a deal. They do give us more information.
If a seller hasn’t received the response they expected, they may be more open to a conversation than they were during the first weekend on the market. That could mean a different purchase price. It could mean help with certain closing costs. It could mean addressing repairs or another term that matters to the buyer.
And sometimes it means nothing at all. The seller may be perfectly willing to wait.
That’s why we look at the history of the individual property instead of assuming that every home with 30 days on market is negotiable.
A Price Cut Tells Us Something
More than four in ten active listings nationally had experienced a price reduction according to HousingWire’s late-September data.
We don’t read that statistic as “buyers should start making low offers.”
We read it as a sign that a meaningful number of sellers have had to respond to the market.
When a property comes on too high, buyers usually notice. When it sits, the seller eventually has a decision to make: adjust the price, improve the terms, wait it out, or take the home off the market.
For a buyer, that history is useful.
Take two similar homes. One was listed three days ago and has already had a busy weekend of showings. The other has been available for six weeks and recently dropped its price. Even if they have similar asking prices today, we probably wouldn’t approach those sellers the same way.
Before our buyers write an offer, EO&A can look at the listing history, comparable sales, competing homes and what has been happening around that particular property. Those details tell us far more than a national headline ever could.
Price Is Only One Thing You Can Negotiate
This is where the conversation gets more interesting.
Most people hear “negotiation” and immediately think about offering less for the house. Sometimes that is exactly where we should focus. Other times, there may be something more valuable to the buyer than another reduction in price.
Last week, we talked about seller-paid rate buydowns and why the same seller dollars can affect a buyer differently depending on how they’re used. That idea applies more broadly.
A buyer who wants to preserve cash may care about an allowable seller credit toward eligible closing costs. Someone concerned primarily about the monthly payment may want their lender to run the numbers on an eligible rate buydown. If a home needs work, repairs could become part of the discussion.
The important thing is to know what would actually help you before deciding what to ask the seller for.
A $10,000 price reduction and a $10,000 seller concession are not interchangeable. They affect the transaction differently, and financing rules can limit how seller contributions are used. This is where having your agent and lender talking to each other before the offer is written becomes incredibly useful.
We can evaluate the property and the negotiation. Your lender can show you what the different options would actually do to your cash to close and monthly payment.
Then we build the offer from there.
What We’re Watching in Northern California
Nationally, inventory has improved from a year ago. Locally, it’s much more complicated.
San Francisco, for example, hasn't followed the same inventory pattern as the country overall. And we wouldn’t expect the market in Marin to behave exactly like Solano, or Napa to behave exactly like Contra Costa.
Even county-level statistics can hide what’s happening at a particular price point or in a particular neighborhood.
A $750,000 home in Napa has a different buyer pool from a $2 million property in Marin. Two neighborhoods in the same city can have different levels of inventory and competition. Move-in-ready homes can behave differently from properties that need significant work.
So when you hear that “buyers have more negotiating power,” add an important qualifier:
Some buyers, on some homes, do.
We think that distinction matters.
The opportunity right now isn’t to assume every seller is desperate. It’s to identify the properties where the circumstances may favor a buyer and be ready when one of those homes fits what you’re looking for.
The Buyers Sellers Want to See
There’s another part of this market that doesn’t get as much attention.
If a seller is willing to negotiate, they still want to know the buyer on the other side can close.
That makes preparation valuable.
Getting fully approved before you find the house gives you a much clearer idea of what you can spend and what the payment will look like. It also means your financing is further along when it’s time to write an offer.
Imagine finding a home that has been sitting for 45 days. The seller has already reduced the price and appears ready to make a deal. That is not the moment you want to start figuring out financing.
You want to be able to look at the house, review the numbers with your lender, talk through the property with your agent and decide whether there is an opportunity worth pursuing.
Being prepared doesn’t mean you have to buy. It means you’re able to act if the right situation presents itself.
Don’t Wait for the Market to Be Perfect
We understand why buyers are watching rates so closely. At more than 7.5%, the cost of borrowing deserves serious consideration.
If the payment doesn’t work for your budget, it doesn’t work. No negotiation strategy changes that.
But if you can comfortably buy at today’s rates, there’s a different question worth asking: What could you potentially gain by shopping while some other buyers are sitting out?
Maybe it’s a home that would have attracted more competition in a lower-rate market. Maybe it’s a seller willing to contribute toward eligible closing costs. Maybe it’s a property that has already gone through a price reduction and is finally within reach.
We don’t know what mortgage rates will do next, and we wouldn’t build a home-buying decision around trying to predict them.
What we can do is pay attention to what sellers and buyers are doing right now.
For anyone looking in Napa, Sonoma, Solano, Marin, Contra Costa, Alameda or San Francisco, EO&A can help you dig into the history and competition around a particular property rather than relying on broad market assumptions.
Get the financing piece handled early. Know the monthly payment that feels comfortable. Then keep an eye on the homes that have been sitting, the ones that have adjusted their price and the sellers who may finally be ready to talk.
Sometimes a changing market creates its best opportunities for the people who are still paying attention.
Happy house hunting 🏡
Sources: Mortgage News Daily and HousingWire Weekly Market Data. Mortgage rates and housing conditions can change quickly. National housing statistics provide broader market context and may not reflect conditions for an individual property or Northern California market.
Common Questions About Buying in a Higher-Rate Market
Are mortgage rates above 7.5% right now?
Mortgage News Daily’s daily rate index ended October 2, 2026, at 7.57% for a top-tier 30-year fixed mortgage scenario. That is a national benchmark rather than a quote available to every borrower. Your actual rate can vary based on your loan type, credit profile, down payment, property and other factors, so current financing should always be discussed directly with your lender.
Are more sellers reducing their asking prices?
HousingWire’s late-September market data showed price reductions on 42.5% of active listings nationally. A price reduction doesn’t necessarily mean a seller will accept another discount, but it can provide useful information about how the market has responded to the property. Buyers should look at the home’s full listing history, comparable sales and competing inventory before deciding how aggressively to negotiate.
Should I look at homes that have been on the market for 30 days or longer?
Yes. A home that has been available for several weeks can be worth another look, particularly if the price has changed or competing properties have come on the market. Longer time on market doesn’t guarantee that a seller will negotiate, but it can change the conversation. Your agent can review the property’s history and surrounding market activity to determine whether there may be an opportunity.
What can I negotiate besides the price of a home?
Depending on the property, seller and financing, an offer may include requests involving allowable seller credits toward eligible closing costs or financing expenses, repairs, or other contract terms. Sometimes a buyer benefits more from one of those terms than from another small reduction in price. Your agent and lender can help compare the options before you decide what to request.
Should I wait until mortgage rates come down to buy?
There isn’t one answer for every buyer. If today’s payment would stretch your budget, waiting may be the appropriate choice. If the payment is comfortable, however, shopping during a period with fewer active buyers may uncover opportunities that aren’t available in a more competitive market. Rather than trying to predict rates, consider your finances, housing needs and the conditions surrounding the specific homes you’re considering.
Search Homes • Explore Financing Resources • Meet the EO&A Team
Contact EO&A today to schedule your free home value review.
Your Trusted Real Estate Advisors across Northern California
Whether you’re planning to sell in San Francisco, Marin, Napa, Sonoma, Solano, Yolo, Sacramento, Contra Costa, or Alameda County, our team has local experts ready to help you navigate your next move with confidence and strategy.
EO&A Team
Elizabeth, Anne, Ian, Ksenia, Cliff, Annie, Mike, Nina, Sidra, Karen, Annie, Steven, Gladys, Venus, Najat, and Courtney
707.312.0819 • hello@eoanda.com • www.eoanda.com
DRE# 01388551 • GUIDE Real Estate DRE# 01976964
Real estate and financing information is provided for educational purposes only. Mortgage programs, rates, qualification requirements, seller concessions, and market conditions can change. Buyers should consult their lender and appropriate professional advisors regarding their individual financial situation.
Anne Kennedy
Broker Associate | EO&A | Real Estate in Napa, Sonoma, Solano, Marin, and San Francisco
or another way