
Categories
Mortgage MinutePublished September 28, 2026
Price Reduction or Rate Buydown? What Northern California Buyers Should Know
Price Reduction or Rate Buydown? What Northern California Buyers Should Know
Mortgage rates moved above 7.4% last week, putting monthly payments back at the center of the home-buying conversation.
At the same time, the information provided for this week’s Mortgage Minute indicates that 42.5% of listings have experienced a price reduction. That combination tells us something important about the current market: affordability is challenging buyers, while some sellers are adjusting to attract them.
A price reduction may seem like the obvious answer. Lower the price and make the home more affordable.
But there are situations where using seller funds differently could have a greater effect on the buyer’s monthly payment, particularly when an eligible buyer and seller can structure a temporary mortgage rate buydown.
For buyers and sellers throughout Napa, Sonoma, Solano, Marin, Contra Costa, Alameda, and San Francisco, this is a good reminder that negotiating a home sale doesn’t have to begin and end with the purchase price.
Higher Rates Are Changing What Buyers Pay Attention To
When mortgage rates rise, buyers naturally become more sensitive to monthly payments.
A buyer may love a home and feel comfortable with the purchase price but hesitate when they see what that price translates to each month. That is why even a substantial price reduction doesn’t always change affordability as much as buyers expect.
Reducing the purchase price lowers the amount being financed, but the buyer is still borrowing at the prevailing mortgage rate. Depending on the transaction, another option may be to negotiate a seller concession and use those funds toward an eligible mortgage rate buydown.
That changes the conversation from simply asking how much a seller is willing to reduce the price to looking at how the available dollars could have the greatest impact for the buyer.
How a 3/2/1 Mortgage Rate Buydown Works
A 3/2/1 temporary rate buydown reduces the effective interest rate used to calculate the buyer’s payment during the first three years of the mortgage.
In the first year, the payment is generally calculated at a rate three percentage points below the note rate. In the second year, the temporary reduction is two percentage points. In the third year, it is one percentage point. After that, the payment returns to the amount based on the original note rate for the remainder of the loan, assuming a fixed-rate mortgage.
For example, if the note rate were 7%, the temporary payment schedule would generally be calculated using 4% during year one, 5% during year two, 6% during year three, and the full 7% beginning in year four.
The mortgage itself still carries the original note rate. The seller-funded buydown provides funds at closing that are used to cover the difference between the temporarily reduced payments and the payments based on the full note rate.
That distinction is important because buyers still need to understand—and be prepared for—the full payment once the temporary buydown ends.
Why a Buydown Can Have a Bigger Immediate Effect Than a Price Reduction
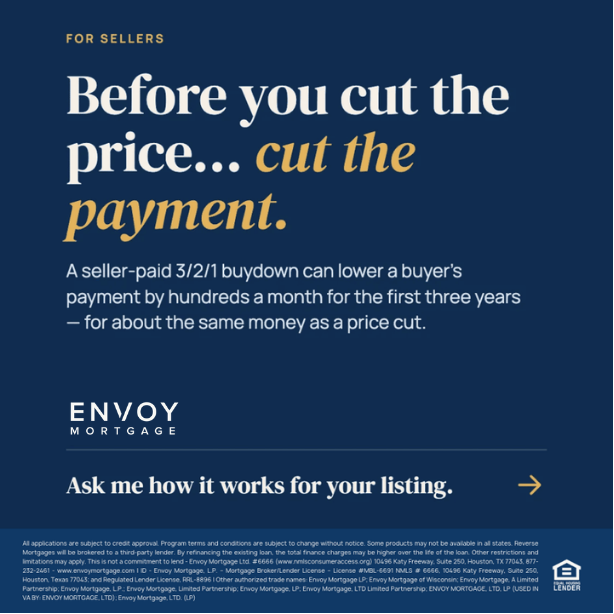
This week’s Envoy Mortgage example illustrates why the comparison is worth running before automatically reducing a home's price.
Using a hypothetical $500,000 home with 10% down and a 7% mortgage rate, the supplied example compares using $20,000 as a price reduction with putting seller funds toward a 3/2/1 buydown.
In the example, the price reduction produces a monthly principal-and-interest payment of approximately $2,874, while the 3/2/1 scenario averages approximately $2,421 per month over the first three years.
That is roughly a $450 difference in the average monthly payment during those first three years under the assumptions used in the example.
It does not mean the buydown is automatically the better financial decision. The lower payment is temporary, and the buyer needs to consider the full loan term, qualification requirements, future payment, and long-term plans.
What the example demonstrates is why buyers and sellers should compare the numbers before assuming a price reduction is the only solution.
This Matters for Sellers, Too
This isn't only a buyer strategy.
For sellers whose homes have been on the market longer than expected, repeatedly reducing the asking price may not always address the concern that is keeping buyers from making an offer.
If buyers like the home but are struggling with the monthly payment, a seller-paid financing concession may be worth discussing alongside a traditional price adjustment.
That doesn't mean a buydown can solve an overpriced listing. If the home is priced above what comparable sales and current competition support, pricing still matters.
But when the home is reasonably positioned and affordability is the bigger obstacle, it can make sense to compare how the same seller dollars affect the transaction when used in different ways.
A seller considering another price reduction can work with their agent and a qualified lender to understand the available options before deciding which approach makes the most sense.
Buyers Can Look Beyond Newly Listed Homes
For buyers, today's market may also reward a little patience within the home search itself.
A home that has been available for several weeks can present a different negotiating opportunity than a property that came on the market yesterday. A listing that has already experienced a price reduction may indicate that the seller is adjusting expectations and is ready to have a more serious conversation about terms.
That doesn't automatically mean the seller will accept another reduction or provide a credit. It simply means there may be more information available to help shape the offer.
EO&A can look at the home's listing history, comparable sales, competing properties, time on market, previous price changes, and current activity before recommending an offer strategy.
Sometimes the opportunity will be price. Sometimes it may be a seller credit. In other cases, the home may already be priced appropriately and there may be little room to negotiate.
The individual property should determine the strategy.
Northern California Markets Require a Local Approach
The same strategy won't work everywhere across Northern California.
A home in Napa that has been available for a month may face very different circumstances from a similar listing in Sonoma, Solano, Marin, Contra Costa, Alameda, or San Francisco. Price point, neighborhood, property condition, competing inventory, and buyer demand all affect how much flexibility a seller may have.
That's why broad headlines about mortgage rates or national price reductions are useful for context but shouldn't dictate an individual offer.
The better approach is to understand what is happening around the particular home.
If similar properties are selling quickly, asking for a significant seller concession may make an offer less competitive. If comparable homes are sitting longer and sellers are adjusting prices, there may be more room to discuss terms.
That local context is what turns a general market trend into an actual buying strategy.
Start With the Payment, Then Build the Offer
For buyers who are actively looking, this is a good time to get very clear about the monthly payment that feels comfortable.
Once that number is established, the lender can model different scenarios. A buyer can see what happens with a lower purchase price, a temporary rate buydown, different down-payment amounts, or other available financing options.
Then the real estate strategy can be built around those numbers.
Instead of automatically asking for $20,000 off the purchase price, for example, the buyer and agent can understand what $20,000 used in different ways would actually accomplish—provided the financing permits it and the seller is willing to negotiate.
That makes the offer much more intentional.
The Best Deal Isn't Always the Lowest Purchase Price
It's easy to look at the final purchase price as the measure of whether a buyer negotiated a good deal.
But the buyer has to live with more than the purchase price.
They have a monthly payment. They have closing costs. They need cash reserves after closing. And they may have repairs, moving expenses, or other costs that come with owning a new home.
In a market where mortgage rates are putting additional pressure on affordability, understanding how all of those pieces work together becomes especially important.
For sellers, it also means thinking beyond the next price reduction. There may be circumstances where a well-structured concession helps address the affordability concern buyers are actually experiencing.
If you're buying or selling in Napa, Sonoma, Solano, Marin, Contra Costa, Alameda, or San Francisco, EO&A can help evaluate the property, current competition, and potential negotiating strategy. A qualified lender can then calculate the financing options and determine whether a temporary rate buydown is available and appropriate.
Before negotiating one number, understand what all the numbers can do.
Happy house hunting 🏡
Sources: Mortgage News Daily; HousingWire Weekly Market Data; mortgage and financing information supplied by Envoy Mortgage. The 42.5% price-reduction statistic and hypothetical 3/2/1 buydown comparison were supplied in this week's Envoy Mortgage materials.
Common Questions About 3/2/1 Mortgage Rate Buydowns
What is a 3/2/1 mortgage rate buydown?
A 3/2/1 buydown temporarily reduces the effective interest rate used to calculate the buyer's payment by three percentage points in year one, two points in year two, and one point in year three. The payment then returns to the amount based on the original note rate. The mortgage's actual note rate does not change, and buyers should understand and be comfortable with the full payment that applies after the temporary period.
Who pays for a 3/2/1 mortgage rate buydown?
In the seller-paid scenario discussed in this week's Mortgage Minute, the seller provides funds at closing to cover the temporary payment reduction. The amount required depends on the loan and buydown structure, and seller contributions are subject to loan-program requirements and limits. Buyers and sellers should have the lender calculate the actual cost and confirm that the proposed contribution is permitted before including a buydown in the purchase agreement.
Is a 3/2/1 buydown better than a price reduction?
Neither option is automatically better. A price reduction permanently lowers the purchase price, while a 3/2/1 buydown temporarily reduces the buyer's payment during the first three years. The better choice depends on the loan, amount of the concession, buyer's finances, expected time in the home, and long-term goals. A lender can compare both scenarios so the buyer and seller can understand how the same amount of money affects the transaction differently.
Does the mortgage rate permanently change with a 3/2/1 buydown?
No. A temporary 3/2/1 buydown does not permanently reduce the mortgage's note rate. Instead, funds provided for the buydown temporarily reduce the payment during the first three years. Once the buydown period ends, payments are based on the original note rate according to the loan terms. Buyers should review the entire payment schedule with their lender rather than making a decision based only on the lower first-year payment.
Can I ask a seller for a mortgage rate buydown?
Buyers can negotiate for a seller contribution toward an eligible mortgage rate buydown, but the seller does not have to agree. The amount and use of seller contributions are also subject to the buyer's loan program and lender requirements. Whether requesting a buydown makes sense can depend on the home's pricing, time on market, competing offers, seller motivation, and the buyer's financial priorities.
Search Homes • Explore Financing Resources • Meet the EO&A Team
Contact EO&A today to schedule your free home value review.
Your Trusted Real Estate Advisors across Northern California
Whether you’re planning to sell in San Francisco, Marin, Napa, Sonoma, Solano, Yolo, Sacramento, Contra Costa, or Alameda County, our team has local experts ready to help you navigate your next move with confidence and strategy.
EO&A Team
Elizabeth, Anne, Ian, Ksenia, Cliff, Annie, Mike, Nina, Sidra, Karen, Annie, Steven, Gladys, Venus, Najat, and Courtney
707.312.0819 • hello@eoanda.com • www.eoanda.com
DRE# 01388551 • GUIDE Real Estate DRE# 01976964
Real estate and financing information is provided for educational purposes only. Mortgage programs, rates, qualification requirements, seller concessions, and market conditions can change. Buyers should consult their lender and appropriate professional advisors regarding their individual financial situation.
Anne Kennedy
Broker Associate | EO&A | Real Estate in Napa, Sonoma, Solano, Marin, and San Francisco
or another way