
Categories
Mortgage MinutePublished October 26, 2026
A Lower Price Isn't the Only Way to Save When Buying a Home
A Lower Price Isn't the Only Way to Save When Buying a Home
Most buyers have a pretty good idea of what they want to spend on a home. They've looked at listings, talked about a down payment, and probably spent more time than they'd like calculating what the monthly mortgage payment might be.
Then they find a home they love, and the conversation turns to price.
Can we offer less? Has the seller reduced the asking price? Is there room to negotiate?
Those are all reasonable things to consider. But there's another number that deserves just as much attention: the amount you'll actually pay each month.
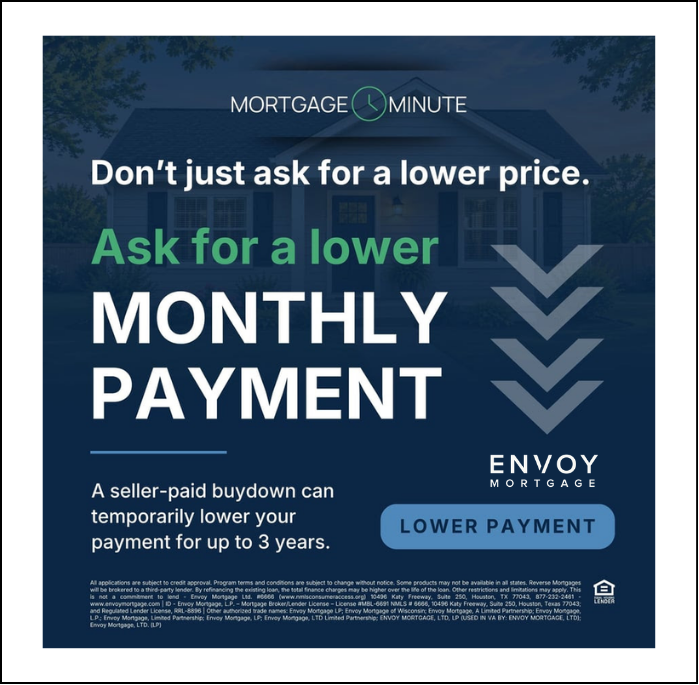
This week's Mortgage Minute from Envoy Mortgage brings that conversation into focus. Mortgage rates have improved for several consecutive weeks, and more than four in ten homes for sale have experienced a price reduction, according to the information provided in this week's update.
For buyers who have been waiting for the numbers to improve, it may be time to revisit what purchasing a home would look like today.
And before asking a seller to lower the price, it may be worth exploring whether a seller-paid mortgage rate buydown could make a greater difference to your initial monthly payment.
What a Few Weeks of Lower Rates Could Mean
Mortgage rates have been a major part of the homebuying conversation for quite some time. Buyers have watched rates move, recalculated payments, adjusted budgets, and sometimes decided to wait.
According to this week's Envoy Mortgage update, rates have improved for several weeks in a row.
That doesn't tell us what will happen next. Mortgage rates can change, and a few weeks of improvement aren't a promise that they'll continue moving in the same direction.
But if you received a mortgage estimate a month ago, the numbers you were working with may already be different.
Consider someone who found a home they liked earlier this fall but decided the monthly payment was a little too high. They may have assumed that purchasing would only make sense after a significant drop in mortgage rates.
Now, with rates having improved somewhat, it may be worth asking their lender to update that estimate.
The difference might be small. It might not change their plans at all. Or it could bring certain homes closer to a payment they're comfortable with.
The point isn't to chase every movement in mortgage rates. It's to make decisions using numbers that reflect what's available to you now.
The Part of Negotiating Buyers Sometimes Miss
When a seller reduces the asking price, it's easy to see the benefit. The home costs less, and the buyer may need to borrow less money.
But the effect on the monthly payment isn't always as significant as people expect.
A price reduction lowers the amount financed, assuming the down-payment structure stays the same. That can reduce the mortgage payment and the overall cost of the home.
A temporary mortgage rate buydown works differently.
Instead of reducing the purchase price, funds are used to temporarily lower the effective interest rate applied to the buyer's payment during the beginning of the loan.
For a buyer who's especially concerned about their initial monthly payment, that can be an option worth discussing.
This doesn't mean a buydown is always better than a price reduction. A lower purchase price has lasting value, while the payment relief from a temporary buydown eventually ends.
The question is which option makes more sense for the buyer's finances, plans, and loan.
That's a conversation worth having before writing an offer.
How a Seller-Paid Mortgage Rate Buydown Works
A seller-paid temporary rate buydown is a financing arrangement in which the seller contributes funds at closing to help reduce the buyer's mortgage payment for an initial period.
The program highlighted in this week's Mortgage Minute describes temporary payment relief for up to three years.
During that period, the buyer makes payments calculated using a temporarily reduced rate. The buydown funds cover the difference between those payments and the amount due under the mortgage's original note rate.
Once the temporary period ends, the buyer makes the full payment required by the original loan terms.
For example, a buyer might have a fixed-rate mortgage with a temporary payment reduction during the first three years. The exact reduction, cost, and payment schedule depend on the program offered by the lender.
The important thing to understand is that the original mortgage rate hasn't permanently changed.
A temporary buydown isn't a substitute for being able to afford the home at the full payment. Buyers should review that payment with their lender before deciding whether this financing option is appropriate.
For someone who is comfortable with the long-term mortgage payment but would appreciate some breathing room during the first few years of homeownership, it may be worth exploring.
Those first years often come with expenses beyond the mortgage itself. Moving, furnishing a home, and taking care of improvements can all require money.
Having a lower initial payment may help some buyers manage that transition, provided the financing fits their overall budget.
Why the Timing Matters This Fall
There are two parts to this week's market update that make the conversation especially relevant.
The first is the recent improvement in mortgage rates.
When the starting mortgage rate decreases, an eligible temporary buydown may produce a lower initial payment than a comparable buydown structured when the note rate was higher.
The second is what's happening with sellers.
According to the information Envoy shared this week, more than four in ten homes for sale have experienced a price reduction, a higher share than at the same time last year.
That figure reflects the broader market information supplied with the update, not a specific percentage for Napa or the surrounding Northern California counties.
Still, it provides useful context. Some sellers are adjusting their expectations, and buyers may have opportunities to discuss terms beyond the asking price.
Imagine finding a home that has been listed for several weeks. The seller has already reduced the price, but the property still hasn't sold.
Rather than automatically requesting another reduction, a buyer could ask their agent and lender to evaluate whether an allowable seller contribution toward a temporary rate buydown would be worth considering.
The seller may prefer one approach over another. The buyer may discover that a lower purchase price is still the better choice.
Either way, comparing the options before negotiating gives everyone a clearer understanding of what the proposed terms would accomplish.
The Right Offer Depends on the Home
A seller-paid buydown isn't something buyers should expect to receive with every purchase.
A well-priced home that has just come on the market may attract strong interest, leaving little room for concessions. Another property may have been available for several weeks and experienced one or more price adjustments.
Those are different situations, and they call for different conversations.
This is particularly important across Northern California, where housing conditions can vary considerably from one community to another.
A buyer searching in Napa may be considering a different price range and property type than someone looking in Fairfield, Santa Rosa, Benicia, Walnut Creek, Oakland, or San Francisco.
Even within the same neighborhood, two homes can have very different listing histories and levels of buyer interest.
At EO&A, we look at the individual property before deciding what kind of offer to recommend.
Has the asking price changed? How long has the home been available? What comparable properties are currently competing for buyers? Does the property need repairs or updates?
Those details help determine whether there may be an opportunity to discuss price, seller contributions, or other terms.
We can evaluate the real estate side of the transaction while the lender calculates the financing options.
That way, the buyer isn't simply asking for a concession without knowing whether it would actually help.
Start With the Payment You Want to Live With
One of the most useful things you can do before making an offer is decide what monthly housing payment feels comfortable.
Not simply what you might qualify to borrow, but what fits your finances while still allowing room for savings, everyday expenses, and the things you enjoy doing.
That number gives your home search a much clearer direction.
From there, your lender can calculate what different purchase prices and financing arrangements would mean for your payment.
If a seller-paid buydown is available, ask to see the full payment schedule, including what happens when the temporary reduction ends.
It's also worth comparing the buydown with a traditional price reduction. The amount a seller is willing to contribute, the cost of the buydown, and the buyer's long-term plans all affect which option may be more beneficial.
For buyers who paused their search when mortgage rates were higher, this is also a good opportunity to request updated financing estimates.
You may find that your original price range still makes sense. You may decide to adjust it. Or you may discover that a home you previously ruled out deserves another look.
There's no need to make that decision based on assumptions when your lender can show you the numbers.
A Better Conversation Before You Make an Offer
Buying a home is a significant financial decision, and it's natural to want the best possible terms.
But the best terms aren't always the ones that produce the lowest purchase price.
For some buyers, reducing the amount borrowed will be the priority. Others may benefit from preserving cash at closing or exploring a financing option that temporarily reduces the monthly payment.
The right answer depends on your circumstances.
This week's Mortgage Minute is a reminder that mortgage rates have improved recently, sellers are making price adjustments, and buyers may have more than one way to approach negotiations.
If you're looking for a home in Napa, Sonoma, Solano, Marin, Contra Costa, Alameda, or San Francisco, EO&A can help you evaluate the properties you're considering and determine where a conversation about seller concessions may be appropriate.
Your lender can then show you how the different options affect your actual payment, both now and in the years ahead.
Before deciding how much less to offer, find out what the available financing options could mean for your monthly budget.
You may discover that the most useful number to negotiate isn't just the purchase price.
Happy house hunting 🏡
Source: Weekly Mortgage Minute update and graphic provided by Envoy Mortgage, with mortgage-rate commentary attributed to Mortgage News Daily. The market figures are presented as supplied and are not specific to individual Northern California counties. Temporary buydown availability, seller-contribution limits, loan qualification, and financing terms depend on the lender and loan program.
Frequently Asked Questions About Seller-Paid Mortgage Rate Buydowns
What is a seller-paid mortgage rate buydown?
A seller-paid mortgage rate buydown is an arrangement in which the seller contributes funds at closing to help temporarily reduce the buyer's mortgage payment. The buydown funds cover the difference between the reduced payments and the payments required under the original mortgage terms. The duration and amount of the reduction depend on the program. Buyers should review the full payment schedule and confirm eligibility with their lender.
Can a seller-paid buydown lower my mortgage payment for three years?
Some temporary mortgage rate buydown programs can reduce a buyer's payment for up to three years, as described in this week's Envoy Mortgage update. The payment reduction changes according to the program's schedule, and the buyer eventually returns to the payment based on the original mortgage note rate. Buyers should confirm the available program, costs, and full payment requirements with their lender before making an offer.
Is it better to negotiate a lower home price or a mortgage rate buydown?
Neither option is automatically better. A lower purchase price permanently reduces the amount paid for the home, while a temporary rate buydown can reduce mortgage payments during the initial years of the loan. The better choice depends on the buyer's finances, the cost of the buydown, the available seller contribution, and long-term plans. A lender can compare both options before the buyer decides what to negotiate.
Can I ask for a seller-paid buydown on a home that has reduced its price?
Yes, a buyer can request an eligible seller-paid mortgage rate buydown when making an offer, including on a home that has already reduced its asking price. However, the seller isn't required to agree, and financing programs have rules about seller contributions. The property's listing history, competition, and seller's circumstances may influence the negotiation. Your agent and lender can help determine whether the request is appropriate.
Should I update my mortgage preapproval when rates improve?
It's worth contacting your lender for updated numbers if mortgage rates have changed since your original preapproval or payment estimate. Even a modest rate improvement may affect the estimated monthly payment, although the actual difference depends on your loan and financial circumstances. Reviewing your current options can help you determine whether to restart your search, adjust your budget, or continue waiting.
Search Homes • Buyer Services • Meet the EO&A Team
Contact EO&A today to schedule your free home value review.
Your Trusted Real Estate Advisors across Northern California
Whether you’re planning to sell in San Francisco, Marin, Napa, Sonoma, Solano, Yolo, Sacramento, Contra Costa, or Alameda County, our team has local experts ready to help you navigate your next move with confidence and strategy.
EO&A Team
Elizabeth, Anne, Ian, Ksenia, Cliff, Annie, Mike, Nina, Sidra, Karen, Annie, Steven, Gladys, Venus, Najat, and Courtney
707.312.0819 • hello@eoanda.com • www.eoanda.com
DRE# 01388551 • GUIDE Real Estate DRE# 01976964
Information is provided for general educational purposes. Property availability, pricing, and open-house schedules can change. Confirm current details with a licensed real estate professional.
Anne Kennedy
Broker Associate | EO&A | Real Estate in Napa, Sonoma, Solano, Marin, and San Francisco
or another way